How to Accept Card Payments in Person
10 mins read
Updated: null
Unlock convenience and boost sales with in-person card payments. Explore the benefits and how-tos of accepting cards today.
Start taking card payments now
The imminent ‘death’ of cash is sometimes over-exaggerated in the media, but there’s little doubt that, in the 21st century, if you want to maximise your revenue, you need to have the widest array of payment options possible available to your customers. The days of being able to insist on customers paying cash (or even specific brands of credit card) are just about over, and businesses that don’t move with these times will find themselves missing out on valuable business.
Ways to Accept Card Payments in Person
Card payments have been an option for retailers since the 1970s, but the technology has changed enormously since then, with a plethora of options now available for customers, who are increasingly expecting retailers and traders to offer the widest selection possible.
Here are some of the most common ways retailers can accept card payments in person, along with their benefits and drawbacks.
Traditional Card Machines (Chip and PIN)
A Chip and PIN card is a type of payment card that requires the cardholder to authorise the transaction by entering their personal identification number (PIN). Chip and PIN technology is used for both debit and credit cards and is less susceptible to fraud than the magnetic stripe cards that came before it. The chip is more difficult to clone and can hold far more information. The main drawback is human fallibility - a customer can’t use Chip and PIN if they can’t remember their PIN.
Contactless Payments
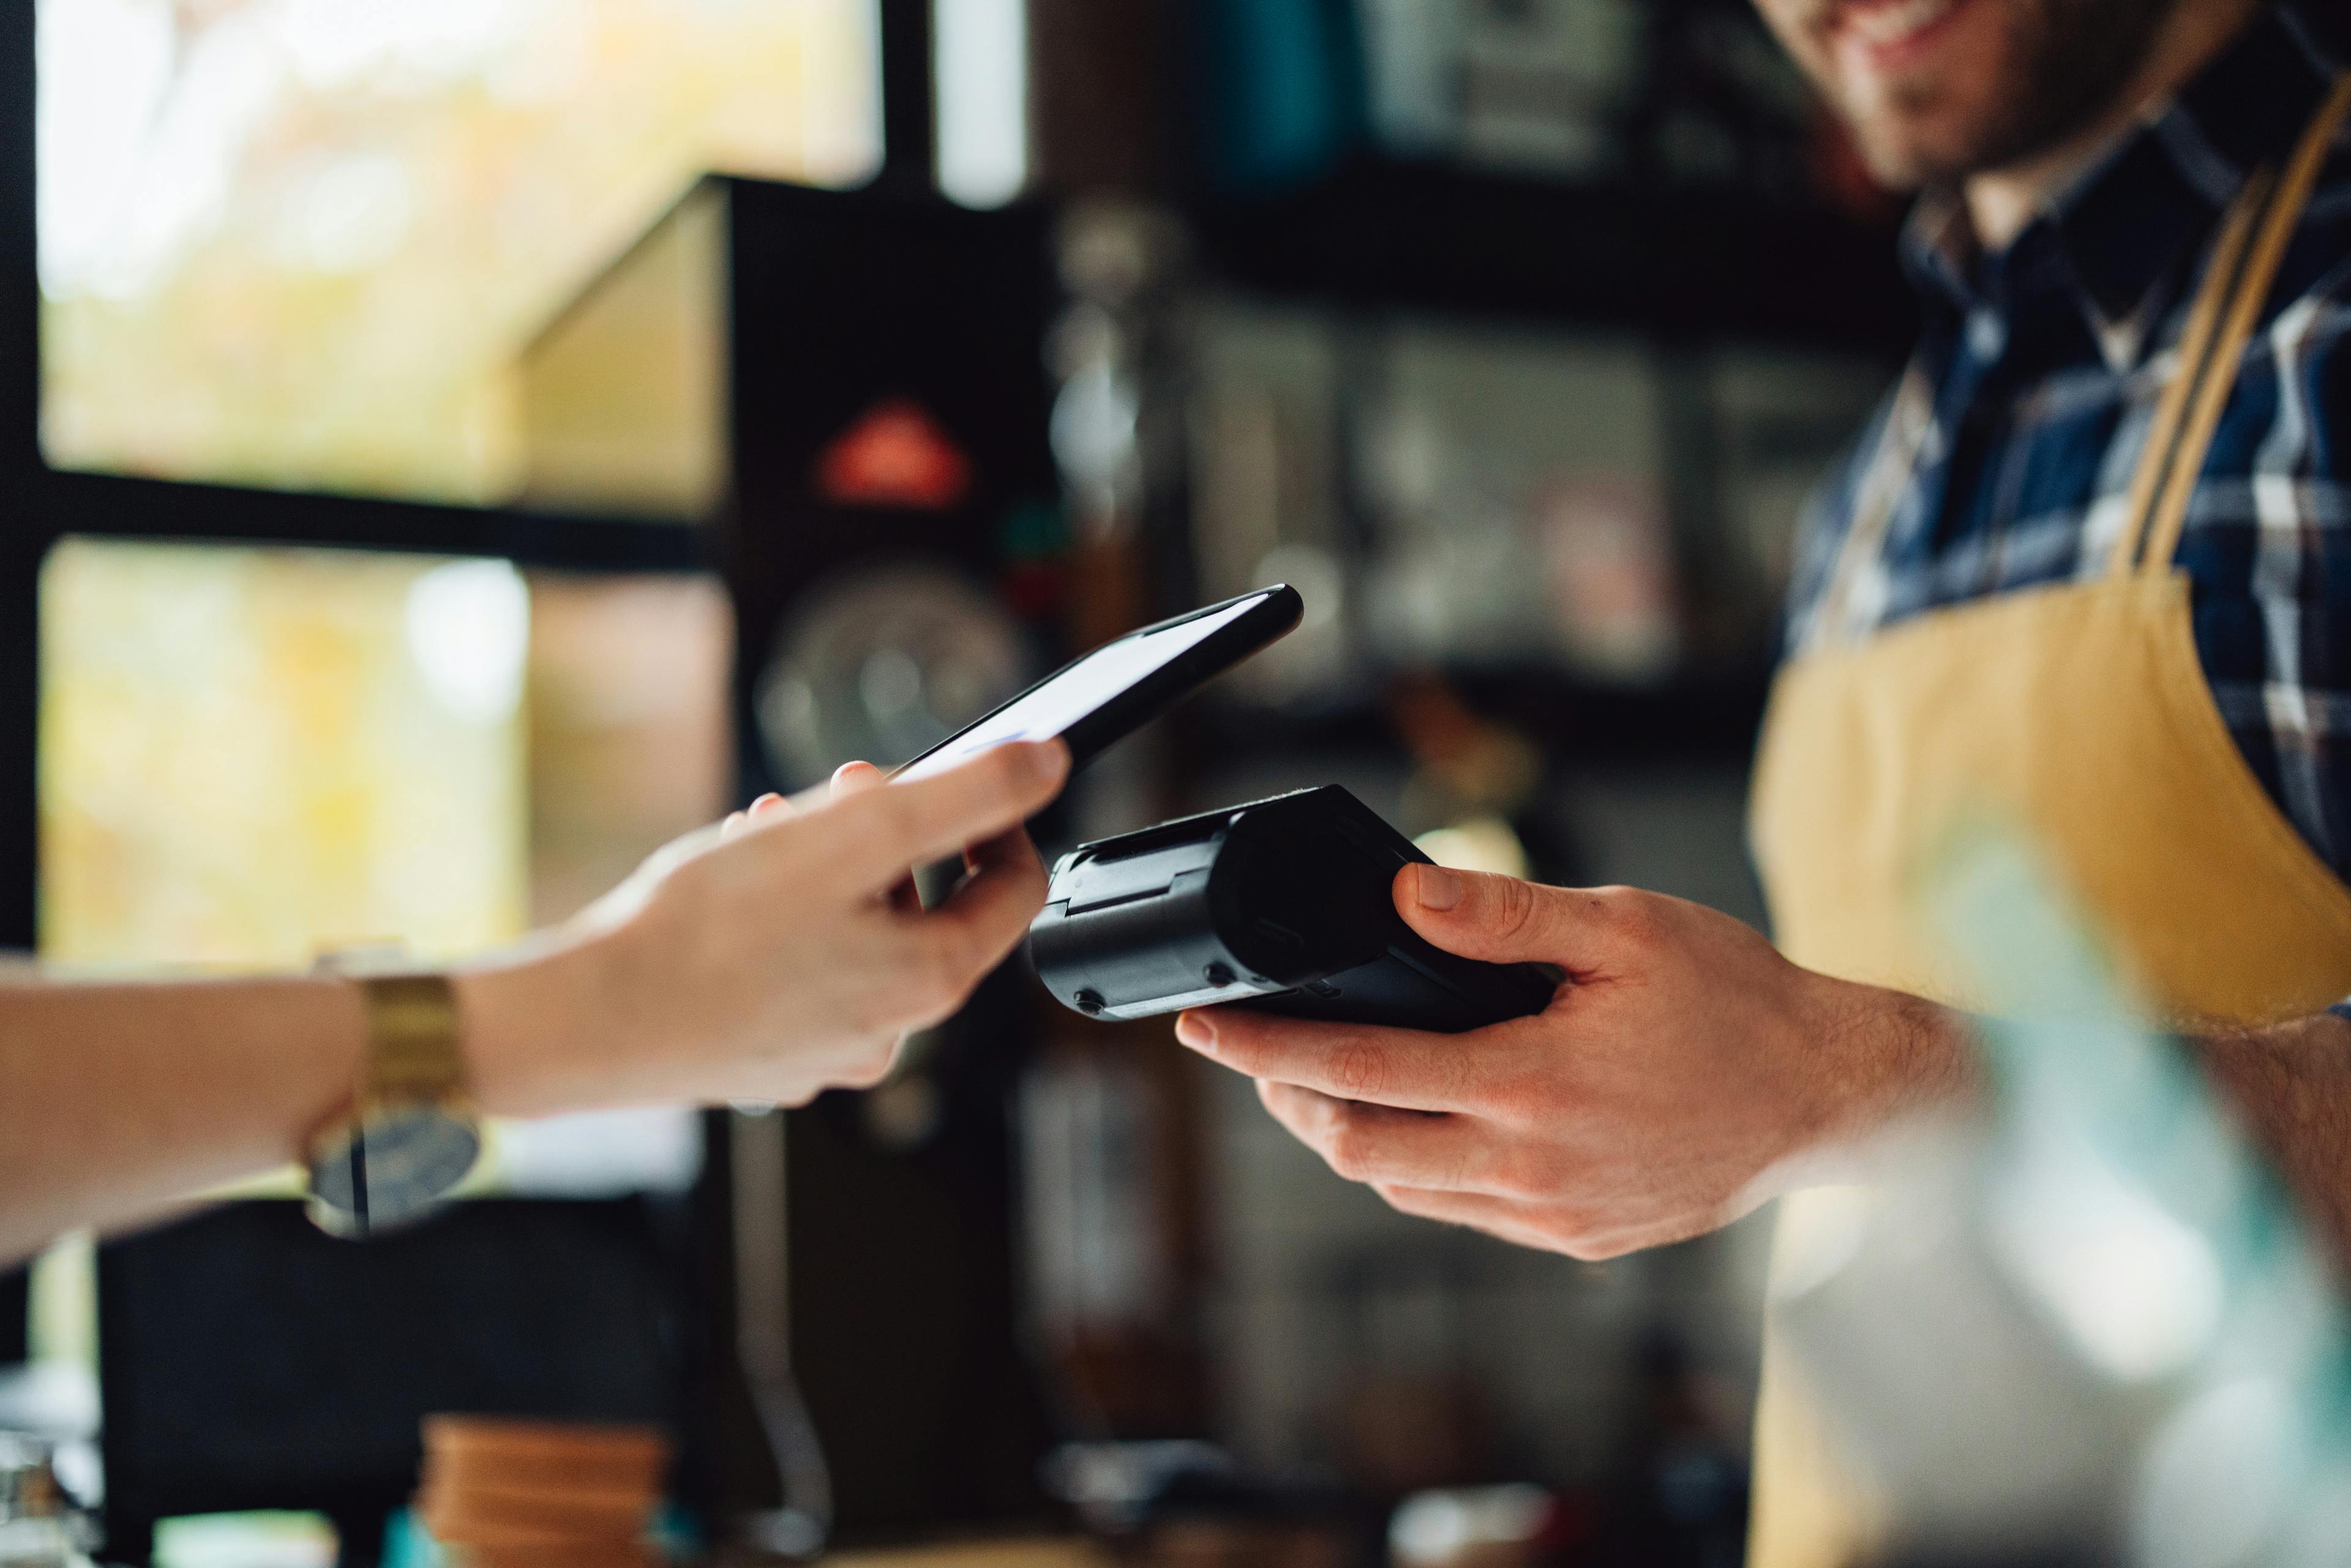
Chip and PIN felt like a great leap forward when it was introduced in 2004, but payment technology has continued to evolve. The main benefit of contactless is speed; transactions are faster, which helps to keep queues moving. For retailers, the processing fees are typically the same as for a Chip and PIN transaction, so the advantage is in customer convenience and throughput, not cost. There are security considerations; because contactless payments below the limit don’t require a PIN, a lost or stolen card can be used for fraudulent transactions until it is cancelled. For this reason, individual contactless payments are capped at £100. While card issuers can set their own lower limits, £100 is the standard transaction limit across the UK.
Mobile Payment Solutions
An increasing number of customers now use digital wallets on their mobile phones, such as Apple Pay and Google Pay. For businesses, accepting them is a simple way to offer more convenience. Most modern card terminals that accept contactless payments also accept mobile wallet payments via the same NFC (Near-Field Communication) technology, so a separate investment is rarely needed. Mobile payments are also highly secure; they use tokenization to hide the real card details and are typically protected by the phone’s own security, such as a fingerprint or face ID. This also means they are not subject to the £100 contactless limit.
Online Payment Gateways for In-person Transactions
Providers like Stripe, Adyen, and Braintree offer services that combine payment processing with hardware for in-person sales and gateways for online sales. This unified approach allows a business to use one provider for all its transactions. These systems support multiple payment methods, including cards and digital wallets, and offer a secure, user-friendly experience for customers. On the downside, they can be more expensive than traditional merchant accounts, with a mix of monthly and per-transaction fees. Customer service can also vary; whilst some providers offer comprehensive support, others may rely more heavily on email or online help centres.
Choosing the Right Payment Processing Equipment
It’s essential for a company to choose reliable payment processing equipment. Reliable payment processing will greatly impact the efficacy and success of sales transactions. Your company and your customers can mutually reap the rewards of a trustworthy payment processor that makes the payment process safe, simple, and hassle-free. For taking payments in person, you will need a POS (Point-of-Sale) system and a card reader, but what combination you want depends very much on what you intend to do with it.
POS Systems
‘Point-of-Sale’ has more than one meaning in retail, but in this case, we’re referring to systems of hardware and/or software that facilitate customer purchases for businesses. Modern POS systems are highly sophisticated. They can update inventory, track sales, print receipts, scan barcodes and QR codes, clock employees in and out, run reports on sales and other analytics, and manage customer accounts and rewards.
Card Readers
The card reader is the part of the POS system that communicates with the customer’s card or device. It securely transmits payment information to your payment service provider and receives confirmation that the payment is approved. Modern readers accept payments contactlessly, via Chip and PIN, and from digital wallets like Apple Pay. While they may still have a magnetic stripe reader for older or foreign cards, this method is almost entirely phased out in the UK for security reasons. You may not need a full POS terminal; for a sole trader like a builder or hairdresser, a simple card reader paired with a smartphone app is often all that’s required.
Setting Up Secure Payment Processing
The specifics of what you need to do in order to set up secure payment processing will depend on the specifics of your business needs, but broadly speaking you’ll need to follow these steps to get yourself set up properly:
Understand Your Customers
In order to set up in-person payment, you first need to understand what payment methods best suit your customers. Not all customers are created equal; some prefer the speed and convenience of contactless payments or digital wallets, while others may prefer to pay by card in a more ‘traditional’ sense. What works best for them will ultimately work best for you.
Understand Your Business
Consider the nature of your sales. What is your average transaction value? If you frequently sell items over the £100 contactless limit, ensuring your setup smoothly handles Chip and PIN or mobile wallet payments (which are not subject to the same limit) is crucial. Also, think about where you do business. A fixed shop or restaurant needs a countertop system, whereas a mobile trader like a plumber or market stallholder needs a portable, battery-powered card reader that connects to a smartphone.
Choose a Payment Service Provider
The job of a payment service provider is to take your customers from the initiation of a payment to its acceptance or refusal in the quickest possible manner. A good PSP should support all major credit and debit cards, digital wallets, local payment methods, online banking, and more. You’ll reach more people and improve the customer experience if they can also pay with digital wallets such as Apple Pay, Google Pay, Click to Pay and PayPal.
Implement Security Features
The security of your customers' data is a top priority. When you accept card payments, you must comply with the Payment Card Industry Data Security Standard (PCI DSS). However, your compliance burden can be significantly reduced by using modern, approved payment terminals and providers. These systems use point-to-point encryption (P2PE), meaning sensitive card data never actually enters your own till or computer systems, and is handled entirely by your provider. This dramatically simplifies your security responsibilities, but you must still ensure your provider is fully compliant and follow their security guidelines.
Obtain the Required Certifications
Your payment provider is responsible for ensuring the hardware and software they provide are certified to the required standards. For in-person payments, this means terminals must be EMV certified, which is the global standard for chip-based payments (from Europay, Mastercard, and Visa). This is not something you need to apply for yourself; it is a core part of your provider's offering. You should, however, always use the equipment supplied by your provider and keep its software up to date.
What Are PCI DSS Standards?
PCI DSS stands for Payment Card Industry Data Security Standards. They are a set of general practices - governed by the major credit card companies - intended to ensure that cardholder information is transmitted, stored and handled securely. They set out the technical and operational requirements for any organisation that accepts or processes payment transactions, as well as manufacturers and developers involved in the production of devices or applications that are used in these transactions.
Understanding Payment Processing Fees
All of this convenience comes at a cost, and it is absolutely critical to the profitability of your business that you understand these costs if you’re to successfully make the transition to accepting the widest range of payment methods possible. These fees are, broadly speaking, divided into two types: those incurred for each specific transaction and monthly or one-off costs charged for payment services and hardware.
This can get complicated, but transaction fees typically fall into two models. Some providers offer a simple, flat percentage for all card types, often between 1.5% and 2%. Others use a more complex ‘Interchange++’ model where the fee varies by card. In either case, the total fee, often called the Merchant Service Charge, is made up of three main components:
Acquirer Fees
This is the fee your payment provider (the acquirer) charges to cover their own costs and profit margin. It is also known as the acquirer markup. This is the only part of the transaction fee that is directly set by your provider and is potentially negotiable. It is typically a small percentage, often well under 1%, but varies considerably between providers.
Interchange Fees
These are the card transaction fees that card acquirers pay to issuers each time a card is used to buy goods or services. They are normally a fixed percentage and non-negotiable. Typical interchange fees are 0.2% for debit cards and 0.3% for credit cards for UK consumer cards, but these rates are normally higher for commercial cards.
Scheme Fees
These are paid by card acquirers to the operators of card payment systems such as Mastercard, Visa and UnionPay to cover their maintenance costs for providing their payment network. The total scheme fee is composed of assessment fees, cross-border fees, clearing and settlement fees. The card type used and the geographical location of the acquirer will affect the total amount charged.
There is room to minimise these fees. Not all card payment fees are created equal; you can save money by accepting card payments in person, as payments by phone or over the internet are considered higher-risk and often incur higher fees. Remember to use the correct Merchant Category Code (MCC). The MCC is a four-digit number used to categorise business types. Whilst interchange fees are fixed by card type, your MCC can influence your provider’s risk assessment of your business, which may in turn affect the acquirer markup they are willing to offer you.
Best Practices for a Smooth Transaction Process
Collect In-Person Payments if Possible
In-person card payments have far lower rates of fraudulent use and chargeback than those made remotely, so if possible, have payments made face-to-face. Multiple chargebacks are expensive and can even jeopardise a processor’s willingness to continue to work with you, so it’s important to keep those to a minimum.
Confirm ID Where Appropriate
For in-person payments, the primary methods of identity confirmation are Chip and PIN for inserted cards and device authentication (like Face ID) for mobile wallets. Asking a customer for separate photo ID is highly unusual for card payments in the UK and is not standard practice. The extra steps mentioned, like one-time passcodes, are part of Strong Customer Authentication (SCA) and apply mainly to online, not in-person, transactions.
Use the Correct MCC
Using the correct Merchant Category Code (MCC) will ensure that you’re charged the correct amount in fees by the processor.
Be Flexible with Payment Methods
When you don’t offer a full range of payment methods, the likelihood is that you will miss out on sales. For all the talk of fraud and the like, the overwhelming majority of payments are made legitimately, so make sure that you understand your customers and what payment methods will work best for them.
Use a Recognisable Business Name and Purchase Description
One of the biggest reasons for returns and potentially very expensive chargebacks is that a customer simply doesn’t recognise a transaction on their bank or credit card statement. You can minimise this by making it absolutely clear who you are and what they’re paying for at the point of sale.
Provide Easily Found Information for Customer Support, Disputes, and Other Issues
Telling customers to just ‘call the bank’, should they have queries or complaints about the service they’ve received, is unlikely to net you any repeat custom from them. Providing customers with prompt and considerate customer service will help prevent them from escalating disputes and increase their trust and confidence in you.
Update POS if You’re Using Legacy Hardware and Software
Relying on old, outdated technology increases your security risks, as well as increasing the likelihood of transactions not being successfully processed. New hardware and software developments secure your business against known vulnerabilities, and continuing to rely on older technology can be a false economy; some of these protections will not be present, increasing the risk of processing fraudulent transactions.
Provide Receipts and Confirm Deliveries
Receipts are an absolute must. Make sure that yours are issued promptly and with all the information required for the customer to be able to identify your payment on their statement. If you’re delivering items, ensure that you have all the documentation to demonstrate that the transaction and delivery concerned were properly completed.
Integrating With Online Payments
Payment gateways enable businesses to accept payments both online and in person. However, choosing the right payment gateway can be a challenge, as pricing and transaction fees differ, and so do the features and inclusions.
How to Choose the Right Payment Provider
Choosing the right provider involves asking several key questions. What’s your budget for hardware and fees? What are you selling, and what’s your average transaction value? How do your customers prefer to pay? The good news is that SwitchPal can help! We simplify the process, working with a panel of trusted payment processors to find the right deal and equipment to suit your business needs.
A cashless society remains some way off, but the days of being able to demand that customers pay by cash are a fading memory. Whilst security is always a consideration, modern payment systems have come along in leaps and bounds in recent years. By offering the payment methods your customers expect, your business could benefit from increased satisfaction and sales, streamlined accounting, and improved cash flow. Get started now, and you too could be benefiting from bringing your payment systems up to date.
Start taking card payments now
Related Guides & Tools
Card Machines and Mobile Card Readers for Small Businesses
Empower your small business with card machines and mobile card readers. Explore options, benefits, and boost sales seamlessly with modern payment solutions.

How to Accept Card Payments Over the Phone
Have you considered accepting card payments over the phone? Discover the steps for implementation, and improve business flexibility and customer convenience.

A Guide to Mobile Card Readers: Which is Right for You?
Discover the best mobile card readers for your business needs. Explore features, compatibility, and pricing to find the perfect option for seamless transactions.
Guides
Get In Touch
© Switch Pal Limited 2026
All rights reserved. Switch Pal Limited is registered in England & Wales: 12545529
Registered address: 66 Paul Street, London, EC2A 4NA
Made with 💜 in London, UK